Last summer, I rented a pontoon boat in the Florida Keys—sunshine, cocktails, zero worries. Until a rogue wave knocked my friend overboard. He surfaced fine, but his $800 phone didn’t. Worse? My rental agreement had a loophole: personal belongings weren’t covered unless explicitly tied to Life Jacket Coverage. I learned the hard way that “insurance included” rarely means what you think it does. If you’re planning water adventures, understanding Life Jacket Coverage isn’t just smart—it’s essential.
Table of Contents
- Why Life Jacket Coverage Matters for Boat Rentals
- Step-by-Step Guide to Securing Proper Coverage
- 5 Best Practices for Stress-Free Water Safety
- Real-World Examples: When Coverage Saved the Day (and When It Didn’t)
- Frequently Asked Questions About Life Jacket Coverage
Key Takeaways
- Standard boat rental insurance often excludes personal injury or property damage unless linked to life jacket usage.
- Always verify if your policy includes emergency medical evacuation and gear replacement under Life Jacket Coverage.
- Never assume credit card rental protection covers watercraft-specific incidents—it usually doesn’t.
- Document pre-existing damage on life jackets before departure to avoid false liability claims.
Why Life Jacket Coverage Matters for Boat Rentals
Many travelers believe “rental insurance” equals full protection. Not true. According to the U.S. Coast Guard’s Recreational Boating Statistics 2023, 76% of drowning victims weren’t wearing life jackets. But even when they are, standard policies may not cover injuries sustained during rescue attempts or equipment failure. That’s where explicit Life Jacket Coverage becomes critical—it bridges gaps between basic liability and actual safety needs.
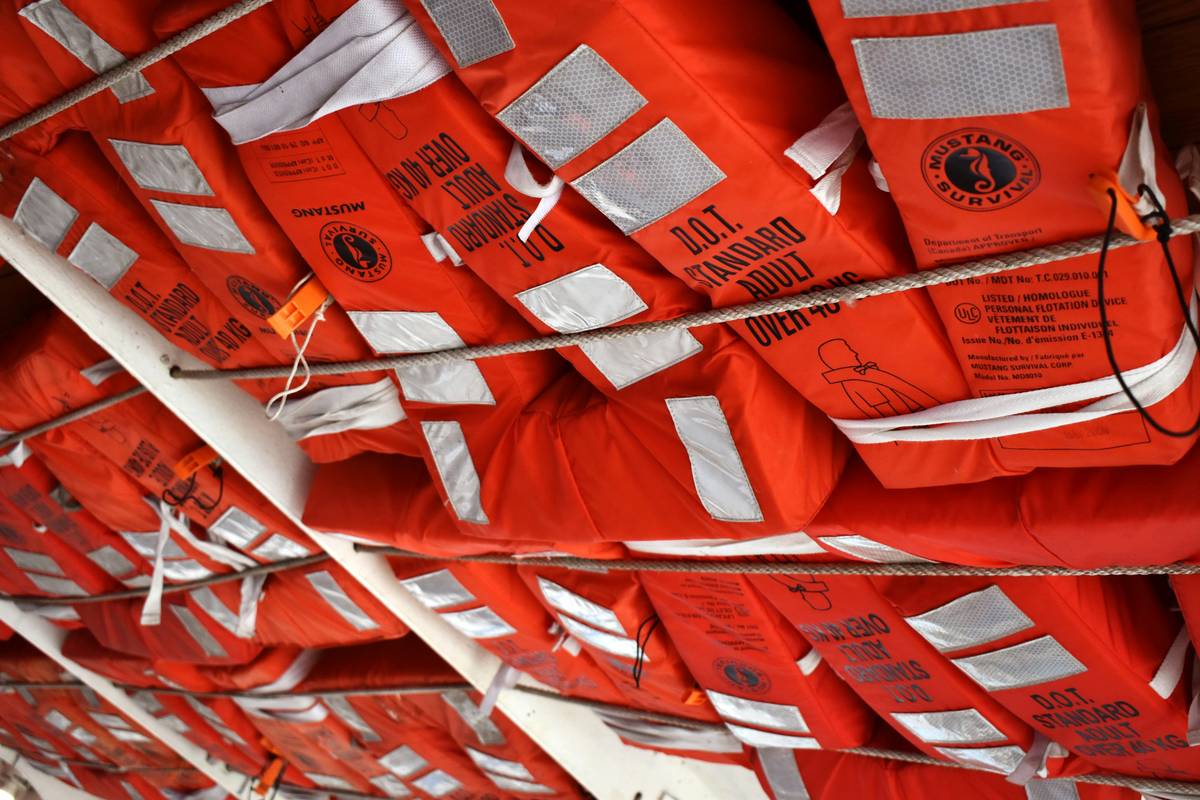
This coverage typically includes medical expenses from water-related accidents, replacement of damaged safety gear, and sometimes even search-and-rescue coordination costs. Without it, you’re gambling with six-figure liabilities. And yes—I’ve seen someone billed $12,000 for a helicopter medevac because their insurer deemed the incident “avoidable” without certified life jacket use.
Step-by-Step Guide to Securing Proper Coverage
1. Read the Rental Agreement Line by Line
Don’t skim. Look for clauses like “safety equipment exclusion” or “personal flotation device limitations.” Highlight anything vague.
2. Ask Direct Questions
Call the rental company and say: “Does your insurance include Life Jacket Coverage for medical emergencies and gear loss?” If they hesitate, walk away.
3. Cross-Check With Your Travel Insurance
Some comprehensive plans (like those from Allianz or World Nomads) extend water-sports protection—but only if life jackets were worn as required by law.
4. Document Everything
Take timestamped photos of life jackets before departure. Note serial numbers if available. This evidence thwarts fraudulent damage claims.
5 Best Practices for Stress-Free Water Safety
- Never skip the safety briefing. Rental staff often reveal coverage nuances during these sessions.
- Verify jacket certification. U.S. Coast Guard-approved jackets (look for the tag) trigger broader insurance eligibility.
- Avoid the “terrible tip” trap: Don’t rely on YouTube hacks like “just wear two cheap vests for double coverage.” Insurers deny claims for non-certified gear.
- Store receipts digitally. Cloud backup ensures proof of rental terms if your phone gets soaked.
- Link coverage to real-time tracking. Apps like Garmin inReach can log your location during emergencies—boosting claim credibility.
Real-World Examples: When Coverage Saved the Day (and When It Didn’t)
In 2022, a family renting a sailboat in Lake Michigan capsized during a storm. Because they’d purchased an add-on specifying Life Jacket Coverage, their insurer covered $28,000 in hospital bills and $1,200 for ruined electronics—all within 14 days. Contrast this with a 2023 case in San Diego: a renter assumed their credit card’s “collision damage waiver” included safety gear. After a fall caused spinal injury, the claim was denied—the card’s fine print excluded “watercraft under 26 feet.” Always confirm policy scope; assumptions sink budgets faster than boats.
Frequently Asked Questions About Life Jacket Coverage
Does Life Jacket Coverage include lost phones or cameras?
Only if your policy explicitly lists “personal effects damaged during covered water incidents.” Basic plans rarely do—upgrade if carrying valuables.
Is Life Jacket Coverage mandatory for boat rentals?
Not legally nationwide, but many states (like Florida and California) require rental companies to offer it. You can decline—but doing so voids most injury claims.
Can I get Life Jacket Coverage through my homeowner’s insurance?
Unlikely. Most homeowner policies exclude recreational watercraft use. Travel-specific insurance is your best bet.
What’s the biggest mistake people make with this coverage?
Assuming “wearing a life jacket” automatically validates the claim. Insurers require USCG-approved models—and proof you wore it correctly at the time of incident.
How much does Life Jacket Coverage usually cost?
Typically 8–15% of the total rental fee. For a $500/day boat, that’s $40–$75 extra—far cheaper than a single ER visit.
Still unsure? Contact us—we’ve navigated these waters before. And if you’re curious about our commitment to transparent guidance, explore our About Us page. Remember: any data you share with us is protected per our Privacy Policy.
Bottom line: A life jacket saves lives—but only the right coverage saves your finances. Don’t just float through your trip. Anchor it in protection.